

Payday Advance Borrow Money
Shpuryk Sergii
- 4.7
- 187.00 Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
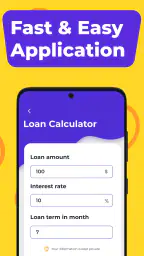
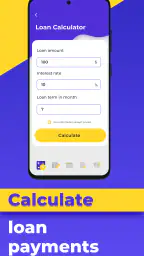
Payday Advance Borrow Money Pros and Cons
Pros
- Fast application process with quick decisions for urgent financial needs.
- Clear repayment schedules help users understand upcoming payment obligations.
- Available entirely from a mobile device without visiting a physical branch.
- May help cover unexpected expenses when other options are unavailable.
- Simple interface makes loan details easy to locate and review.
Cons
- Interest and fees can make the total repayment significantly higher.
- Short repayment periods may be difficult for users with limited income.
- Approval, loan amounts, and terms may vary by location and applicant.
- Late payments could lead to additional charges or negatively affect finances.
- Some features may require sharing sensitive personal and financial information.
 Analysis by All-app
Payday Advance Borrow Money is a finance app from Shpuryk Sergii that is designed to help people look for a suitable payday cash advance. I approached it as a practical borrowing tool rather than a general money-management app, and that distinction matters. Its purpose is narrow: it can help organize the first step of a short-term borrowing search, but it should not replace careful checking of the final lender, repayment terms, or your own budget.
The app is free to install and is rated for Everyone, which makes it approachable for a broad audience. It has built a solid level of interest, with over 100K installs and a 4.7 average from around 2.8K ratings. Those figures suggest that many people find the basic experience useful, although popularity should never be treated as proof that a particular advance is affordable or suitable for every borrower.
How I used the app for a realistic borrowing search
My baseline workflow was simple. I opened the app with a specific need in mind, such as covering an unexpected household bill before the next regular payday. Instead of treating the first available option as an answer, I used the app as a starting point for comparing possibilities. That mindset is important because a payday advance can solve a timing problem while creating a larger repayment problem later.
The most useful habit is to decide the amount and repayment date before browsing. Without that boundary, it is easy to focus on how quickly money might arrive and forget whether the repayment fits comfortably alongside rent, utilities, food, transport, and existing commitments. I would write down the actual shortfall first, then search only for an amount connected to that shortfall.
Payday Advance Borrow Money is best understood as an entry point into the process. It does not turn borrowing into free money, and the app itself should not be confused with the lender that may ultimately provide an offer. When I reached a decision point, I treated every lender detail as something to inspect separately rather than assuming that an app result automatically represented the cheapest or safest choice.
That approach also answers one practical question new users often have: can the app guarantee approval? I would not use it with that expectation. A search or advance-oriented app can help you find an option, but approval, eligibility, repayment conditions, and the final cost depend on the lender and the individual application. The sensible workflow is to use the app to narrow the search, then read the lender’s own terms before accepting anything.
What the first pass does well
The app’s focused purpose is its main strength. Someone looking for a short-term cash advance does not have to begin with a full banking suite, investment dashboard, or complicated budgeting system. The experience is aimed at a particular moment: finding a possible payday borrowing route when time feels limited.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
I also found that the narrow focus encourages a more deliberate sequence. First identify the need, then review the available route, then check the repayment obligation. That is healthier than opening a general financial app and jumping between unrelated tools while under pressure. The free price removes an installation barrier, but it does not remove the financial cost that may come with borrowing, so I would keep those two ideas completely separate.
Another useful point is that the app runs on Android devices using at least version 5.0. That gives it a broad technical reach, including older phones that may not support newer finance applications. The current version is 1.2.1, so I would still keep the app updated through the normal store process and use a device with a screen lock when handling any financial information.
Settings and checks worth making before searching
There are no settings I would casually change just to make the app feel faster. In a borrowing context, speed is not always the goal. I would first check the device’s notification behavior, the app’s access settings, and the privacy controls available on the phone. If notifications are enabled, I would make sure they cannot expose sensitive financial details on a lock screen.
This is a small but important habit: review what appears when a notification arrives. A shared phone, family tablet, or workplace environment can make even an ordinary reminder more revealing than expected. I would use private lock-screen previews and avoid leaving application screens open when stepping away from the device.
I would also check whether the app is being used in the correct country and financial context before relying on any result. Payday lending rules, lender availability, costs, and eligibility can vary by location. If the app presents a route that does not clearly match where I live, I would stop and verify the lender independently rather than entering personal information simply because the process looks convenient.
One of my strongest recommendations is to prepare a small repayment note outside the app. Record the amount you plan to borrow, the date your income arrives, the expected repayment amount, and the bills due before then. This is not a glamorous feature, but it is an advanced user habit because it prevents the app from becoming the only place where the decision exists. If you cannot explain the repayment in one clear sentence, you probably need more information before continuing.
Faster patterns that still leave room for judgement
Experienced users can make the process quicker without rushing the decision. I would keep a reusable checklist in my notes application: exact amount needed, repayment date, total repayment, lender identity, and what happens if repayment is late. That checklist turns every new search into the same repeatable process and reduces the chance of overlooking a key term during a stressful moment.
A second useful pattern is to search once, pause, and compare the result with a normal alternative. For a small emergency, that alternative might be asking a trusted person, delaying a nonessential purchase, using an existing overdraft facility, or contacting the bill provider about a payment arrangement. Those options are not automatically better, but comparing them prevents the app from making a payday advance feel like the only available answer.
I would also avoid repeated searches for a larger amount merely because the first figure feels uncomfortable. If the need is a modest shortfall, increasing the request can make the repayment burden harder to manage. A good shortcut is to separate “what would make this situation easier” from “what is actually necessary.” Payday Advance Borrow Money is more useful when it supports that discipline rather than encouraging a larger request.
Another practical habit is to save the final lender details in a secure place only after checking them. Do not rely on memory, especially when comparing several options. Note the repayment date and total obligation, then set a personal reminder through the phone’s calendar. The reminder should be earlier than the due date, giving you time to act if your income or circumstances change.
Where convenience reaches its limits
The biggest limitation is built into the type of product the app helps users find. A payday advance is generally associated with short repayment periods, and that can be a poor match for an ongoing financial gap. If you are borrowing to cover the same expenses every month, the app is not solving the underlying problem. A longer-term budgeting conversation, debt advice service, or lower-cost credit option may be more appropriate.
I would also be cautious if the repayment depends on uncertain income. A freelance payment, delayed wage, benefit decision, or pending transfer may not arrive when expected. In that situation, a promised repayment date can be less reliable than it appears. The app may help locate a possible advance, but it cannot make uncertain income predictable.
Users should ask whether they are comfortable sharing personal information during the application journey and should read each screen carefully. I would never assume that an app’s free installation means the borrowing itself is free. Before accepting an offer, check the total amount to repay, any applicable charges, the due date, and the consequences of missing it. If those details are difficult to find or understand, that is a reason to pause rather than press ahead.
There is also a difference between a convenient search tool and a full financial service. Someone who wants transaction tracking, spending categories, savings goals, or detailed debt planning may find a traditional banking app or budgeting application more useful. Payday Advance Borrow Money is not the right choice for managing an entire financial life; its value is concentrated in the search for a short-term advance.
Who should use it, and who should skip it?
I can see this app helping a user who has a clearly defined, temporary cash gap and wants a focused place to begin comparing payday advance possibilities. It may also suit someone using an older Android phone, since the minimum operating-system requirement is relatively accessible. The free installation makes it easy to inspect the experience without paying upfront for the app itself.
I would skip it if the borrowing need is recurring, if the repayment would leave no room for ordinary living costs, or if you are already juggling several debts. In those cases, another short-term advance can deepen the pressure. I would also choose a different type of finance app if my goal were to build a monthly budget, monitor spending, or improve savings habits rather than search for emergency credit.
Age suitability deserves a careful interpretation. The app carries an Everyone content rating, but that does not mean every person can legally qualify for a payday advance. The store rating describes app content, while lender eligibility is a separate matter. I would treat those as two different checks and never infer borrowing eligibility from the age label alone.
My final view after testing the workflow
Payday Advance Borrow Money is a focused, free finance app for the early stage of looking for a payday cash advance. Its strongest quality is simplicity: it addresses a specific borrowing search instead of pretending to be a complete financial command center. The developer, Shpuryk Sergii, has positioned it around a practical need, and the strong average rating shows that the focused concept has attracted positive user response.
My recommendation comes with a firm condition: use it as a comparison and discovery tool, not as permission to borrow. The best experience comes from combining the app with a written repayment plan, a notification privacy check, an independent look at lender terms, and a comparison against non-borrowing alternatives. Those habits make the process faster without making it careless.
If you need a one-time bridge and already know exactly how repayment will work, Payday Advance Borrow Money can be a convenient place to begin. If your income is unstable, your debts are already difficult to manage, or you need broader money-management features, I would choose a different financial route. In my view, the app is most useful when it helps you make a controlled decision—and least useful when urgency is allowed to make the decision for you.
Frequently Asked Questions
What is Payday Advance Borrow Money?
Payday Advance Borrow Money is a financial app designed to help eligible users request short-term cash advances through a mobile device. It may provide an estimate of available funds, repayment information, and application status within the app. Availability, approval, loan amounts, and terms can vary depending on your location, financial profile, identity verification, and the specific lending partners involved.
How does the borrowing process work?
After installing the app, you generally create an account, provide personal and financial information, verify your identity, and review any available offer. Before accepting, carefully check the repayment date, fees, interest or annual percentage rate, and total amount due. Once approved, funds may be sent to a linked bank account, although delivery times can depend on your bank and the selected service.
What fees and repayment terms should I expect?
The cost of using Payday Advance Borrow Money depends on the offer presented to you and may include service charges, finance fees, expedited-transfer fees, or other costs. Repayment terms can also differ, so do not rely only on the advertised advance amount. Read the complete agreement before accepting, confirm the total repayment amount, and make sure the scheduled payment fits comfortably within your budget.
Is Payday Advance Borrow Money available to everyone?
No. Access is usually subject to eligibility requirements that may include minimum age, residency, a valid bank account, identity verification, income information, and other lending criteria. The app may not be available in every country or state, and submitting an application does not guarantee approval. Check the official terms, privacy policy, and local regulations before entering sensitive financial information.
Is it safe to use the app, and what should I check first?
Before using Payday Advance Borrow Money, download it only from an official app store and verify the developer, reviews, permissions, and privacy practices. Never share banking credentials through unofficial messages or pay an upfront fee to guarantee approval. Also consider alternatives such as a bank, credit union, employer advance, or financial counselor, because short-term borrowing can become expensive if repayment is missed.


